Consider Daniel. At 41, he earns more than he ever expected to.
His career is established. The expensive debt is gone. His monthly spending is comfortably below his income. He has built the cash reserve that once seemed impossibly large.
And every month, more money arrives than his life consumes.
By most measures, this is success.
But Daniel has developed a new financial problem.
His cash balance keeps growing, and he is increasingly unsure what to do with it.
Part of him likes seeing the money there. It represents security. Years ago, an unexpected expense could have destabilized an entire month. Now he can absorb one without much thought.
Another part of him worries that he is being too cautious.
He reads about markets rising. Friends talk about properties, private investments, businesses, and opportunities. Financial media reminds him that cash loses purchasing power over time.
So occasionally he invests.
A little here.
A larger amount there.
But there is no real system behind the decisions.
Sometimes he waits too long because doing nothing feels safe.
Sometimes he acts too quickly because doing nothing begins to feel irresponsible.
Daniel has learned how to create surplus.
He has not yet learned how to govern it.
That distinction marks one of the most important transitions in building wealth.
The Builder learns how to make money survive consumption.
The Investor must decide what that surviving capital should become.
The surplus is not the strategy.
It is the raw material from which the strategy must now be built.
The Builder’s Success Creates the Investor’s Problem
The Builder has an essential job:
Create distance between income and consumption.
Without that distance, there is no meaningful capital base.
Income arrives. Expenses absorb it. The next month begins. The financial system remains dependent on continued effort.
The Builder changes that equation.
Income is no longer entirely consumed.
Some of it survives.
That survival creates surplus.
And surplus creates capacity.
It can build reserves.
It can reduce dependence on debt.
It can absorb disruption.
It can create optionality.
Eventually, it can become productive capital.
But every financial stage eventually creates the problem of the next one.
The Builder asks:
How do I create more excess capital?
The Investor begins asking:
What job should this capital perform?
That is a different question because it requires a different skill.
Saving is largely about restraint.
Investing is about allocation.
The habits that created the surplus do not automatically tell you what to do with it.
The Surplus Trap
Once a meaningful surplus exists, two opposite mistakes become possible.
The first is keeping too much capital idle simply because holding cash feels safe.
But there is an important distinction here.
Cash is not inherently unproductive.
A reserve that prevents you from selling long-term investments during an emergency is doing important work.
Cash intended for a known obligation is doing important work.
Liquidity that gives you time, flexibility, or negotiating power is doing important work.
There is a difference between intentional liquidity and unresolved capital.
Intentional liquidity has a job.
Unresolved capital is waiting for one.
The problem begins when money continues accumulating not because you have deliberately decided that it should remain liquid, but because you do not yet have a framework for deciding what should happen next.
Eventually, that discomfort can produce the opposite mistake.
Urgency.
The money has been sitting there too long.
Markets are moving.
Someone mentions an opportunity.
A friend is making money somewhere.
Suddenly the pressure is no longer to protect the capital.
It is to do something with it.
That creates a dangerous sequence:
Surplus → discomfort → urgency → deployment → hidden risk
Movement feels like progress.
But capital does not become productive simply because it leaves a bank account.
Undirected buying does not eliminate fragility.
It merely relocates it.
The problem behind both extremes is the same.
The capital has no governing system.
Why High Earners Can Stay Here for Years
High income can make this problem surprisingly difficult to recognize.
A physician, executive, consultant, or entrepreneur can make poor capital decisions and still appear financially strong.
Why?
Because another large paycheck arrives.
A loss can be replaced.
An unnecessary expense can be absorbed.
A poorly considered investment can be repaired with future earnings.
The system appears resilient because the Earner keeps replenishing it.
But resilience and replenishment are not the same thing.
Resilience means the financial system can absorb a mistake or disruption without threatening its underlying structure.
Replenishment means labor repeatedly repairs whatever the system loses.
The distinction matters.
If every financial mistake can be solved by another year of hard work, the system may be wealthy while remaining dependent.
That dependency can be comfortable.
It can even be lucrative.
But it is still dependency.
If labor must repeatedly rescue capital, capital has not yet become a source of freedom.
The transition into Investor begins when accumulated capital is expected to function with increasing independence from continued labor.
Not immediately.
Financial freedom is staged.
But directionally, responsibility begins moving.
From labor toward capital.
From accumulation toward allocation.
From saving toward stewardship.
Margin of Safety Changes the First Question
The instinct of a new Investor is often to ask:
What should I invest in?
Or:
Where can I earn the highest return?
Those are reasonable questions.
They are simply not the first ones.
Before deciding what an investment might earn, the Investor needs to understand what the capital is supposed to do.
Start with purpose.
What is this money for?
Then time.
When might I need it?
Then downside.
What happens if I am wrong?
That final question is especially important.
Markets fall.
Businesses fail.
Assets underperform.
Income changes.
Plans turn out to be wrong.
The objective of a financial system cannot be to eliminate every bad outcome.
The objective is to prevent an ordinary bad outcome from becoming a catastrophic one.
That is the purpose of a margin of safety.
It creates distance between disappointment and destruction.
This is Capacity Before Compounding.
Compounding requires return.
But before it requires return, it requires survival.
Capital must remain invested long enough for time to matter.
A household that has to sell investments every time life becomes expensive cannot compound consistently.
A portfolio dependent on leverage may not survive the period required for the investment thesis to work.
A concentrated position can contain an excellent asset and still threaten the larger financial system.
The investment matters.
But so does the architecture surrounding it.
A good asset cannot rescue a bad structure.
The Surplus Conversion Sequence
Once the stability floor exists, surplus can begin moving through a deliberate sequence.
The exact allocation will differ depending on income stability, obligations, taxes, dependents, risk capacity, and time horizon.
The principle, however, remains useful:
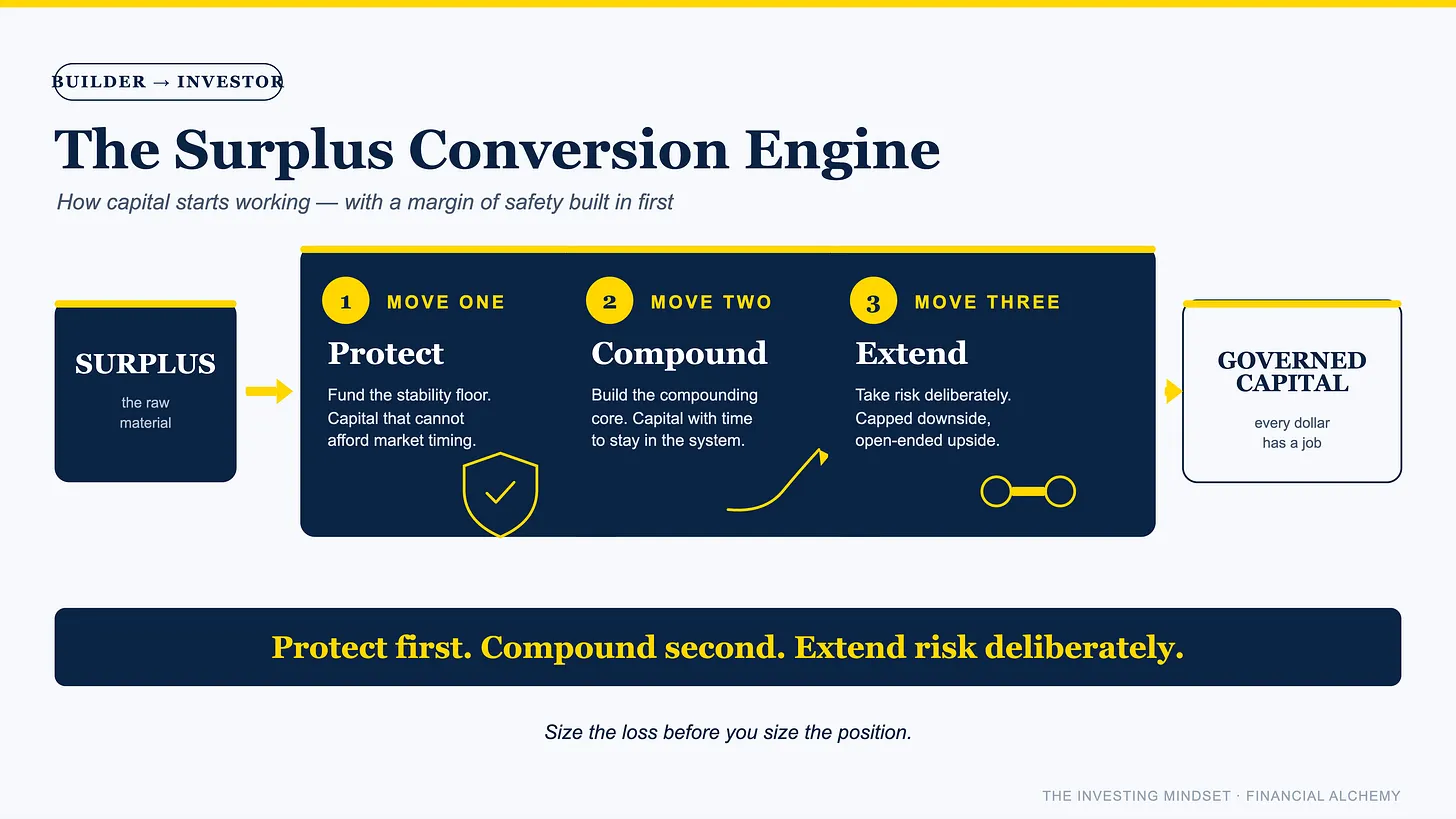
Protect first. Compound second. Extend risk deliberately.
Move 1: Protect What Must Remain Protected
Before asking what should be invested, identify what should not be exposed to long-term investment risk.
What expenses must the system be able to absorb?
What known obligations are approaching?
How much liquidity does your particular life require?
What risks are large enough that insurance rather than savings should carry them?
This is the stability floor.
Its purpose is not to maximize return.
Its purpose is to prevent long-term capital from being interrupted by short-term life.
A useful question is:
What capital cannot afford market timing?
Money needed next year should not necessarily behave like money intended to compound for twenty years.
Once that distinction becomes clear, cash stops being one undifferentiated pile.
Some capital is protected because protection is its job.
Only after that job has been funded does the next question become useful.
Move 2: Build the Compounding Core
The second destination is long-term productive capital.
This is money whose job is different.
It does not need to pay next year’s tax bill.
It does not need to repair the roof.
It does not need to replace six months of lost income.
Its time horizon allows it to accept uncertainty in exchange for participation in long-term growth.
This is where durable compounding should do most of the work.
The objective is not excitement.
It is sustained participation.
A quieter strategy that can be held through multiple market cycles may create more wealth than an aggressive strategy repeatedly interrupted by fear, leverage, concentration, or financial necessity.
The Investor therefore asks something more useful than:
What could this earn?
The better question is:
What conditions must remain true for me to stay invested long enough to earn it?
Compounding is usually described as mathematics.
But in real life, compounding is also a systems problem.
The capital has to remain in the system.
Move 3: Extend Risk Deliberately
Only after protection and the compounding core are established does higher-variance opportunity belong in the conversation.
A concentrated investment.
A private business.
A speculative position.
An asymmetric opportunity.
These are not necessarily mistakes.
But they should not have the ability to destabilize the rest of the system.
The governing principle is simple:
Size the loss before you size the position.
Before committing capital, ask what happens if the thesis is completely wrong.
Not temporarily wrong.
Not down 10%.
Wrong.
If losing that capital would force you to borrow, liquidate the core, abandon important obligations, or depend on future income to repair the damage, the position may be too large for the architecture supporting it.
The Investor is not trying to eliminate risk.
Risk is necessary for productive participation.
The Investor is deciding which risks deserve to be taken and how much of the financial system they are allowed to threaten.
That is a very different exercise from simply looking for the highest expected return.
The Investor’s Real Job Is Governance
This is why owning investments does not automatically make someone an Investor.
A brokerage account does not do it.
Property does not do it.
Sophisticated financial products do not do it.
The transition occurs when capital stops being treated as one pool of money and begins receiving different jobs.
Some capital protects the system.
Some meets known obligations.
Some preserves optionality.
Some compounds over decades.
Some may be exposed to deliberately chosen opportunities.
And each category is judged according to a different purpose.
The Investor therefore becomes three things at once:
A capital allocator.
A risk manager.
A compounding thinker.
That sequence matters.
Because the central question is no longer simply:
What should I buy?
It becomes:
What role should this dollar perform inside the whole financial system?
Once you start asking that question, money begins to behave differently.
Not because there is suddenly more of it.
Because there is architecture around it.
What to Do This Week
You do not need to redesign your entire financial life this weekend.
You need to identify the next unresolved decision.
Here are four places to start.
1. Label your capital
Look at the capital you have accumulated and stop treating all of it as one number.
Ask what each portion is supposed to accomplish.
What protects you?
What will be needed within the next few years?
What exists primarily for optionality?
What genuinely has a long enough horizon to compound?
The objective is not to create fifteen bank accounts.
It is to create clarity about purpose.
2. Find the unresolved cash
Look for money that is sitting in cash without a defined reason.
Do not assume it should immediately be invested.
Ask why it is there.
If the answer is protection, near-term spending, taxes, optionality, or another deliberate purpose, it may already be doing its job.
If the answer is:
I’m not really sure what else to do with it,
you have found unresolved capital.
That is an allocation decision waiting to be made.
3. Ask what happens if you’re wrong
Before making a meaningful investment, run the downside through the entire financial system.
If the investment performs poorly, what changes?
Is it disappointing?
Does it delay a goal?
Does it require additional work?
Does it create debt?
Does it force the sale of another asset?
Does it threaten something important?
Not every loss carries the same consequence.
The Investor’s job is to understand the consequence before accepting the risk.
4. Create a conversion rule
Finally, stop requiring yourself to solve the surplus problem again every month.
Create a rule for what happens when new surplus arrives.
How much replenishes the protective layer when necessary?
How much moves automatically toward long-term compounding?
Under what circumstances can capital move toward higher-risk opportunities?
A system does not need to eliminate judgment.
It should eliminate unnecessary repeated decisions.
That is the beginning of capital governance.
From Accumulator to Allocator
A year from now, Daniel’s financial life does not look dramatically different from the outside.
He still works.
He still earns well.
He still spends less than he earns.
Surplus still appears every month.
But the surplus no longer creates the same low-grade anxiety.
Part of his capital remains liquid because he knows exactly what that liquidity protects.
New long-term capital moves toward his compounding core according to a rule rather than a mood.
And when an interesting opportunity appears, he no longer begins with the possible return.
He begins with the size of the loss his larger system can absorb.
The result is almost boring.
That is the point.
His money has stopped waiting for instructions.
More importantly, he has stopped confusing activity with progress.
The Surplus Was Never the Destination
The Builder’s achievement was learning to make some of today’s income survive into tomorrow.
That achievement matters.
The margin matters.
The reserves matter.
The discipline matters.
But eventually, success creates a new responsibility.
The Investor must decide what that surviving capital becomes.
Some of it should protect you.
Some should preserve your options.
Some should be given enough time to compound.
And some, perhaps, can be exposed to greater uncertainty in pursuit of greater upside.
The sophistication is not in making every dollar move.
It is in knowing which dollars should move, which should wait, and what must remain true for both decisions to survive being wrong.
That is the shift from saving money to governing capital.
The surplus was never the strategy.
It was the raw material.
The strategy begins when every part of that surplus has a job—and when your capital can keep doing that job without needing your next paycheck to rescue it.
So before asking where your next dollar should be invested, ask a more revealing question:
What job does this dollar need to do for the financial system I am trying to build?
If your surplus is growing but you are not sure what should remain protected and what is ready to compound, start by mapping the jobs your capital currently performs. The Financial Clarity Diagnostican help you identify your real monthly number, current surplus, and weakest stability layer.
→ Get the Financial Clarity Worksheet

