Blog
At 6:17 on a Tuesday morning, a physician I’ll call David sits in his car in the hospital parking garage.
The engine is off. His hands are still on the wheel.
The shift is waiting. So are the patients, the inbox, the charting, the staffing problems, and the administrator who measures his productivity in relative value units.
David is exhausted in a way that sleep no longer seems to fix.
For months, he has thought about cutting back.
Four days a week, maybe.
A different group.
A three-month leave.
Anything that might give him enough distance to recover some sense of himself.
But every time he imagines stepping away, another calculation begins.
The mortgage.
The school tuition.
The car payments.
The student loans that followed him out of residency.
The family obligations.
The lifestyle that once felt like evidence that the years of training had finally paid off.
On paper, David earns more than $400,000 a year.
In practice, he cannot comfortably stop earning for even a few months.
So he picks up his bag and walks inside.
This is one part of physician burnout we do not talk about enough.
A difficult job is one problem.
A difficult job you cannot afford to leave is another.
Burnout Without an Exit
Physician burnout has many causes.
The electronic health record matters. Staffing matters. Administrative burden matters. Loss of autonomy matters. Moral injury matters. Depression and other mental health conditions deserve to be taken seriously on their own terms.
Financial stress is not a substitute explanation for any of these things.
But it can change what happens when the work becomes intolerable.
Two physicians can experience the same hospital, the same call schedule, the same leadership decisions, and the same overflowing inbox.
One has twelve months of living expenses in reserve, modest fixed obligations, and enough financial flexibility to reduce clinical time or walk away.
The other has two months of liquidity and a household that depends on nearly every dollar of current income.
Their workload may be identical.
Their experience of that workload may not be.
One thinks:
I could leave.
The other thinks:
I can’t.
That difference is more important than it first appears.
Financial fragility may not create burnout.
But it can turn burnout into captivity.
It removes choices.
And when you have no choices, even temporary problems begin to feel permanent.
The High-Income Paradox
Medicine creates a peculiar financial paradox.
A physician can earn several times the median household income and still be dependent on the next paycheck.
From the outside, that can be difficult to understand.
The salary is high.
The career is prestigious.
The house is comfortable.
Surely financial stress should disappear once income reaches a certain level.
But income is not wealth.
Income is raw material.
What matters is what happens after the income arrives.
A large salary can support a large mortgage, private school tuition, multiple vehicles, student debt, professional expenses, family commitments, travel, second homes, and an expanding collection of recurring obligations.
None of those decisions has to be foolish on its own.
That matters.
Physicians spend much of their twenties and often part of their thirties delaying gratification. While friends in other professions are buying homes, building retirement accounts, traveling, and establishing adult financial lives, physicians are still training.
So when the attending income finally arrives, it is natural to want life to expand.
The house gets bigger.
The neighborhood changes.
The children enter better schools.
The vacations improve.
The cars improve.
After years of postponement, success finally becomes visible.
And because the income is high, every decision appears affordable.
The danger is not one expense.
The danger is cumulative dependence.
When every increase in income becomes permanently absorbed into the cost of maintaining life, a high salary stops creating freedom and begins financing obligation.
That is how golden handcuffs are built.
Quietly.
One reasonable decision at a time.
The Financial Fragility Loop
The mechanism looks something like this:
High income → lifestyle expansion → higher fixed obligations → dependence on the next paycheck → fewer professional exits → greater tolerance of unhealthy conditions → deeper burnout → less energy to build an alternative
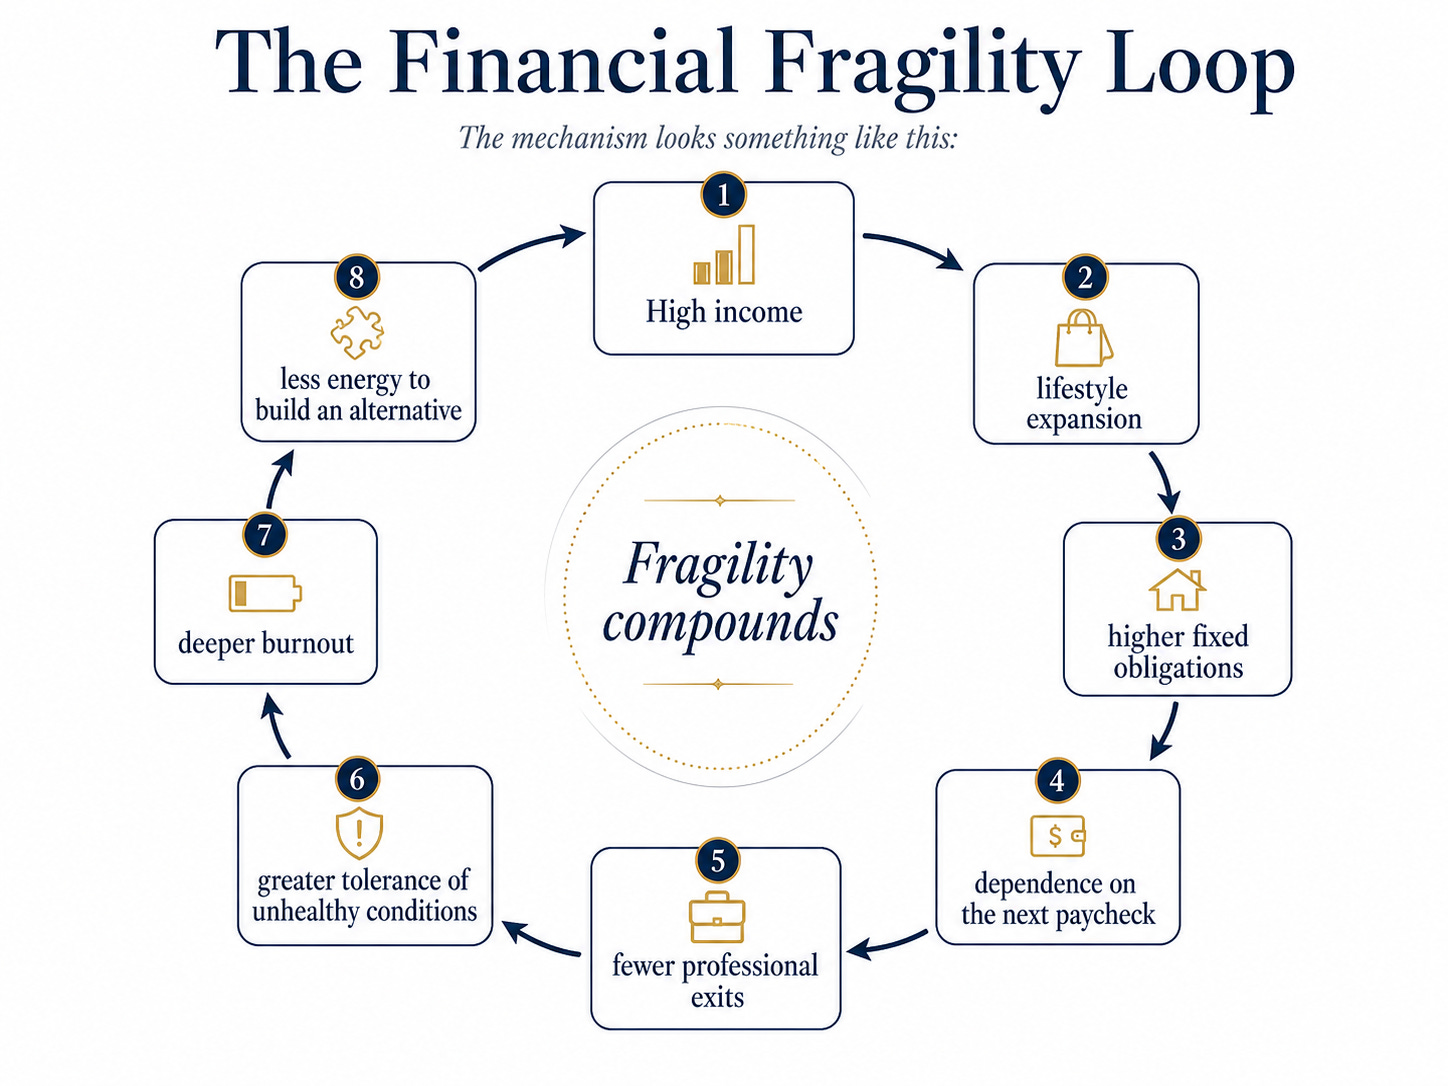
Then the loop begins again.
The cruel part is that it often looks like success from the outside.
The bigger house does not announce itself as a constraint.
It announces itself as an achievement.
The new car does not feel like surrendered optionality.
It feels like a reward.
But every permanent obligation makes a claim on future labor.
And every dollar of future income that has already been committed reduces the freedom to decide how that labor will be spent.
This is why the most important financial question for a high earner may not be:
How much do I make?
It may be:
How much choice does my financial structure create?
The Trap Beneath the Financial Trap
For physicians, money is only part of the problem.
There is also identity.
Medicine does not ask for a small portion of your life.
It asks early, and it asks repeatedly.
You are selected for discipline and delayed gratification.
You spend years studying while your peers are earning.
Then residency consumes much of what remains of your twenties and sometimes your thirties.
By the time full income finally arrives, you are not simply someone who works in medicine.
You are a doctor.
The identity is fused to the self.
That is part of what makes burnout so difficult.
When the work becomes harmful, a physician may not experience leaving as simply changing jobs.
Leaving can feel like abandoning the person they spent twenty years becoming.
It can feel like wasting the sacrifice.
Letting down a family.
Walking away from status.
Betraying patients.
Failing at the thing they were supposed to be able to endure.
So two powerful constraints begin reinforcing each other.
The balance sheet says:
You cannot leave.
Identity says:
You should not want to.
Between them, a physician can stop asking whether the environment is acceptable and begin asking only how much more they can tolerate.
That is a dangerous place to live.
Why Some Burnout Solutions Feel Incomplete
Healthcare systems have become more willing to talk about physician burnout.
That is progress.
There are programs around resilience, mindfulness, scheduling, vacation, inbox management, leadership, staffing, exercise, sleep, and work-life balance.
Some of these interventions help.
Some are necessary.
But they cannot solve financial dependence.
A physician can take two weeks off, sleep better, exercise, meditate, and come back with more emotional capacity.
But if the underlying reality remains—
I cannot reduce my hours.
I cannot take a lower-paying job.
I cannot leave this group.
I cannot step away for six months.
I cannot tolerate a meaningful drop in income.
—then one structural source of stress remains untouched.
Wellness can improve recovery.
It does not automatically create optionality.
And optionality matters because there is a profound psychological difference between:
I have to work here.
and
I am choosing to work here.
The work may be exactly the same.
The relationship to it is not.
The Reframe: Stop Optimizing Only for Income
When high earners begin to feel financially constrained, the instinctive solution is often to earn more.
Another shift. A bigger bonus. More call. More production.
A new investment that promises a higher return.
More income must mean more safety.
But if the additional income simply supports additional obligations, nothing fundamental changes.
The cage gets larger.
It does not disappear.
A more useful goal is this:
Stop optimizing only for a higher income. Start optimizing for lower dependence on that income.
That is a different way to think about wealth.
Financial freedom is not merely the amount of money you earn.
It is the degree to which your life can continue without requiring you to earn at the same rate, under the same conditions, indefinitely.
That kind of freedom begins long before retirement.
It begins with runway.
Your Freedom Runway
One simple measure can reveal far more about financial independence than salary alone.
I call it the Freedom Runway:
Freedom Runway = Liquid Assets ÷ Monthly Essential Expenses
It answers a straightforward question:
If your current income disappeared tomorrow, how many months could your household function without radically changing your life?
Not how long you could survive by selling everything.
Not how long you could get by while panicking.
How much time could your existing financial structure give you to think, recover, negotiate, and choose deliberately?
That number is not a moral judgment.
It is a diagnostic.
A physician with two months of runway and a physician with eighteen months of runway can earn the same salary, work in the same hospital, and live in entirely different psychological worlds.
A useful way to think about the stages is:
Fragile: 0–3 months
The paycheck is still urgent. A job interruption quickly becomes a household crisis.
Stabilizing: 3–12 months
Breathing room appears. A short leave, job transition, or temporary reduction in income becomes possible.
Optional: 1–3 years
Professional choices become materially different. You can negotiate, reduce hours, walk away from an unhealthy environment, or accept a lower-paying role without immediately destabilizing your life.
Ownership: assets increasingly support the life
This is different from simply holding several years of savings. Runway is finite. If you consume it, it disappears.
The deeper form of freedom arrives when assets begin producing enough income or growth to carry more of the household without depending entirely on your labor.
Runway buys time.
Ownership reduces the need to sell that time in the first place.
Two Doctors, Same Salary
Imagine two physicians in the same specialty, living in the same city.
Both earn $400,000.
Both are frustrated with administration.
Both have had enough of inbox messages and productivity targets.
Both are considering reducing their clinical load.
The first physician has two months of liquid reserves and high recurring obligations.
The second spent several years deliberately controlling fixed costs and building eighteen months of runway.
From the outside, almost nothing looks different.
Inside, everything does.
When leadership adds another unreasonable demand, the first physician thinks:
I hope I can survive this.
The second can think:
Do I still want to accept this?
That does not guarantee happiness.
It does not fix healthcare.
It does not make the inbox disappear.
But it restores something burnout often destroys:
agency.
And agency changes the experience of work.
Do Not Turn the Escape Plan Into Another Trap
There is an additional danger here.
When someone feels trapped, urgency becomes a vulnerability.
A burned-out physician who desperately wants to replace clinical income may become attracted to anything promising rapid financial independence.
Highly leveraged real estate.
Speculative investments.
Concentrated bets.
Businesses they do not understand.
Complex strategies promising “passive income.”
The emotional appeal is easy to understand.
If the job feels unbearable, an investment that promises escape can begin to look like rescue.
But adding financial fragility to professional fragility is not freedom.
It is simply a different form of dependence.
The proper sequence is quieter.
Liquidity.
Controlled fixed obligations.
Consistent surplus.
Adequate protection.
Then deliberate investment.
Avoiding ruin precedes optimization.
You do not first need a spectacular investment return.
You need a financial structure strong enough to survive disappointment.
Freedom is rarely built through one home run.
It is built by gradually reducing the number of things you are forced to tolerate.
From Earner to Owner
This is why I think financial freedom is better understood as a progression rather than an event.
Earner → Builder → Investor → Owner
The Earner depends primarily on personal effort. Income may be high, but if the labor stops, the financial engine largely stops with it.
The Builder begins converting income into capacity. The focus is surplus, liquidity, controlled obligations, and runway.
The Investor deliberately turns accumulated capital into productive assets.
The Owner reaches the point where ownership—not simply the next shift—supports more and eventually all of the life.
The destination does not have to be early retirement.
That is too narrow.
The goal is choice.
The ability to work four days instead of five.
To take a sabbatical.
To leave a toxic practice.
To say no to extra call.
To choose the better job even if it pays less.
To remain in medicine because the work is meaningful rather than because the mortgage makes the decision for you.
That is why financial freedom matters long before financial independence.
The Question Is Not Whether You Should Leave
You may not need to leave medicine.
You may not need to change hospitals.
You may not need to sell your house.
And you certainly do not need to redesign your entire financial life tomorrow.
But you should know whether you could.
That distinction matters.
Because burnout feels different when there is a door.
Even if you never walk through it.
So here are two questions worth asking:
If your income disappeared tomorrow, how many months could you live without radically changing your life?
And perhaps the more revealing question:
If that number were ten times larger, what would you no longer be willing to tolerate?
Your answer may tell you something your salary never will.
The goal is not to escape medicine.
It is to build enough financial strength that staying becomes a choice.
If you want to make this practical, start by calculating your Freedom Runway: liquid assets divided by monthly essential expenses. That single number can reveal how much professional optionality your financial life currently gives you.
The Financial Alchemy Diagnostic goes further, helping you identify whether you are functioning primarily as an Earner, Builder, Investor, or Owner—and what your next stage-appropriate move should be.